The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Contract works insurance and public liability insurance protect against different construction risks. This guide explains how they differ, where other builders insurance types fit, and what builders should check before relying on any policy.
Builders, contractors and small construction businesses often hear several insurance terms used together: contract works insurance, public liability, tools cover, plant and equipment cover, professional indemnity and more. They are related, but they do not all protect the same risk.
The short version is this: contract works insurance generally protects the project works and materials during construction, while public liability insurance generally responds to third-party injury or property damage claims. Depending on your trade, contract type, project value and tender requirements, you may need more than one type of cover.
This article explains the main differences so you can ask better questions when reviewing contract works insurance and other construction-related policies in Australia.
Contract works insurance vs public liability insurance at a glance
| Insurance type | Main purpose | Common example | What to check |
|---|
| Contract works insurance | Helps protect the building works, materials and construction project from insured physical loss or damage during the construction period. | A storm damages partially completed works, or materials on site are stolen, subject to the policy terms. | Project value, contract period, insured parties, defects exclusions, theft conditions, existing structures and handover rules. |
| Public liability insurance | Helps protect against claims by third parties for personal injury or property damage connected with your business activities. | A member of the public trips over site equipment, or neighbouring property is damaged by construction activity. | Limit of liability, exclusions, subcontractor arrangements, high-risk activities, contractual liability and site-specific requirements. |
| Tools, plant and equipment cover | Helps protect specified tools, mobile plant or equipment owned, hired or used by the business. | A compressor, generator, excavator attachment or hand tools are stolen or damaged. | Owned versus hired items, storage requirements, transit cover, unattended vehicle exclusions and item limits. |
| Professional indemnity insurance | Helps protect against claims arising from professional advice, design, documentation or consulting services. | A design-related error causes financial loss or rectification costs. | Whether you provide design, engineering, project management or certification-related advice, and whether contractual requirements apply. |
What contract works insurance is designed to cover
Contract works insurance, sometimes called construction works insurance, construction project insurance, site insurance or building works insurance, is generally intended to protect the physical works being built or renovated.
Depending on the policy, it may respond to insured events affecting:
- partially completed building works;
- materials intended to become part of the project;
- temporary works used for the project;
- some off-site storage or transit risks, if included;
- fire, storm, theft, vandalism, malicious damage or accidental damage, where covered by the wording.
The exact scope can vary significantly between insurers and policies. For example, cover for theft may depend on site security, while cover for existing structures may need to be specifically arranged. Some policies are annual policies for multiple projects, while others are arranged for a single contract.
Contract works insurance is particularly relevant where a builder or contractor could be financially responsible if the works are damaged before completion or handover. It can also be a condition of construction contracts, lender requirements or tender documents.
What public liability insurance is designed to cover
Public liability insurance is different. It is generally designed to protect a business against legal liability to third parties for personal injury or property damage arising from business activities.
For a builder or contractor, public liability may be relevant if:
- a visitor, client, neighbour or member of the public is injured because of site activity;
- construction work damages neighbouring property;
- materials or equipment create a hazard that causes third-party loss;
- a subcontractor arrangement or site incident leads to a liability dispute.
Public liability is often described as contractor public liability, construction public liability or business liability insurance. It is an important part of many builders insurance programs, but it should not be treated as a substitute for contract works insurance.
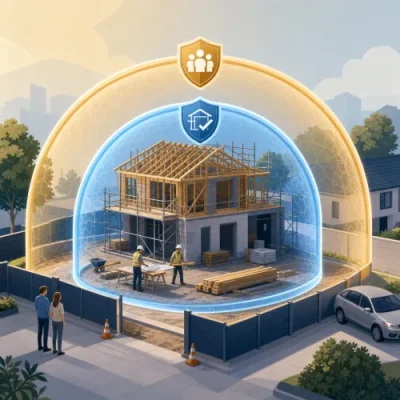
The key difference: the project itself versus liability to others
The clearest way to separate the two is to ask: what has been damaged, and who is making the claim?
- If the construction works or project materials are physically damaged, contract works insurance may be the relevant policy.
- If another person or business claims you caused injury or property damage, public liability insurance may be the relevant policy.
For example, if a severe storm damages partially completed framing on a building site, that is primarily a contract works question. If construction activity damages a neighbouring fence or a passer-by is injured near the site, that is primarily a public liability question.
In real claims, the answer can be more complicated. One incident may involve several policies, exclusions or responsible parties. A policy may also exclude certain defects, faulty workmanship, damage to your own work, or property in your care, custody or control. The wording and circumstances matter.
Why public liability may not protect the works under construction
A common misunderstanding is that public liability insurance will cover any construction-site problem. It generally will not.
Public liability is not primarily designed to rebuild or repair the project you are constructing. If materials are stolen from the site, fire damages the partially completed works, or vandalism affects the project before handover, a public liability policy may not respond simply because no third-party liability claim has been made.
Builders should be careful with assumptions such as "I already have public liability, so the project is covered". That may leave a significant gap if the contract places responsibility for the works on the builder or contractor during construction.
Where other construction insurance types fit
Contract works and public liability are only two parts of a broader construction insurance picture. Other policies may be relevant depending on your role, business structure, employees, equipment and contractual obligations.
Tools and equipment insurance
Tools insurance, plant cover or equipment insurance may protect trade tools, machinery, hired-in plant or portable equipment. This is separate from protecting the building works themselves. A contract works policy may cover project materials but not every tool or item of equipment used to perform the job.
Plant and machinery cover
Contractors using excavators, loaders, cranes, scissor lifts, compressors or other machinery may need specific plant and machinery cover. Cover can differ for owned, hired, dry-hired, wet-hired, registered and unregistered plant.
Commercial motor insurance
Vehicles used in the business may need commercial motor insurance. This is separate from public liability and separate from the construction works. Trailers, utes, trucks and specialised vehicles may require different arrangements.
Professional indemnity insurance
Professional indemnity can be important where a builder, contractor, designer or consultant provides professional advice, design, certification, documentation, engineering input or project management services. A construction defect caused by design advice may not be treated the same way as accidental physical damage to works.
Workers compensation
If your business has employees, workers compensation obligations may apply. Requirements differ across Australian states and territories, and businesses should confirm their obligations with the relevant authority or professional adviser.
Home building compensation or domestic building insurance
Residential builders may encounter home building compensation, domestic building insurance or similar schemes depending on the state or territory and type of work. These schemes are not the same as contract works insurance or public liability insurance.
Do subcontractors need their own insurance?
Subcontractor insurance can be a source of confusion. A head contractor may arrange contract works insurance for the project, and some policies may include subcontractors as insured parties for certain purposes. However, this does not automatically mean every subcontractor has all the cover they need.
Subcontractors often need to consider their own public liability insurance, tools cover, plant cover, motor insurance and any cover required by their subcontract agreement. They should also check whether they are noted or covered under a project policy and what limits, exclusions and responsibilities apply.
Head contractors should avoid assuming that a subcontractor's insurance fills every project gap. Subcontractors should avoid assuming that the head contractor's policy protects their business in every situation.
How tender and contract requirements affect insurance choices
Construction tenders, principal contracts and subcontract agreements often specify insurance requirements. These may include:
- minimum public liability limits;
- contract works insurance for the full contract value;
- cover for temporary works, materials in storage or transit;
- noting principals, financiers or subcontractors as insured or interested parties;
- professional indemnity requirements for design-and-construct work;
- plant and equipment insurance for hired or operated machinery;
- evidence of currency before starting on site.
Do not rely only on the policy name. A tender may use broad terms such as "construction insurance" or "builders insurance", but the actual requirement may be more specific. Builders should review the insurance clauses, policy schedules and certificates of currency carefully.
What affects cost and availability?
Premiums, terms and availability depend on the insurer, broker, policy type and your circumstances. For contract works insurance, relevant factors may include project value, duration, construction type, location, site security, past claims, defect exposure, existing structures and whether the policy is single-project or annual.
For public liability, factors may include business activities, turnover, number of workers, subcontractor use, high-risk work, claims history, liability limit and the environments where work is performed.
If you are reviewing project numbers alongside insurance requirements, the site's calculators may help with general planning. They do not replace policy advice or insurer assessment.
Questions to ask before choosing between policies
In most cases, the question is not whether to choose contract works insurance or public liability insurance. Builders often need to understand how the policies work together.
Useful questions include:
- Who is responsible for the works before practical completion or handover?
- Does the contract require contract works insurance, public liability insurance or both?
- Are subcontractors, principals, owners or financiers required to be noted on the policy?
- Are existing structures included or excluded?
- Are materials covered while stored off site or in transit?
- Does public liability cover the specific activities being performed?
- Are there exclusions for height work, excavation, demolition, hot works, asbestos, design or other higher-risk activities?
- What evidence of insurance must be provided before work starts?
- What excesses, limits, sub-limits and conditions apply?
When to get broker or adviser help
Construction insurance can be technical because several policies may apply to the same project. A broker or qualified adviser can help compare wording, identify gaps and explain how different policies may respond to a claim scenario.
This can be especially useful for builders tendering for larger projects, performing civil works, using subcontractors, working on existing structures, taking on design obligations or managing multiple projects under an annual contract works policy. If you need help reviewing multi-policy requirements, you can use the site's broker information as a starting point.
Bottom line
Contract works insurance and public liability insurance are not interchangeable. Contract works insurance is generally about damage to the project works and materials during construction. Public liability insurance is generally about claims from third parties for injury or property damage caused by your business activities.
Builders, contractors and construction business owners should read policy wording carefully, check contract requirements and consider how different insurance types interact. The right mix of cover depends on the project, business activities, contractual obligations and insurer criteria.
Published: Thursday, 17th Sep 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.