The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Contract works insurance can help protect construction projects against physical loss or damage, but the scope of cover depends on the policy wording, project type, limits and exclusions.
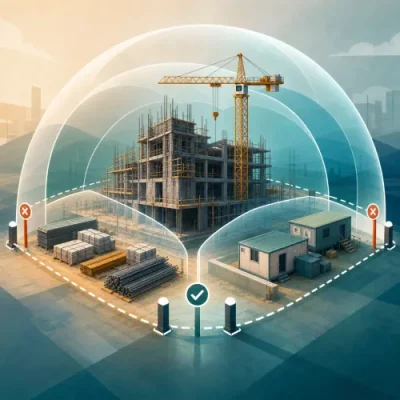
Contract works insurance is designed to protect building and construction projects against certain types of physical loss or damage during the construction period. It is commonly used by builders, contractors, owner-builders and construction businesses that need cover for a specific project or for multiple projects under an annual policy.
The exact answer to what does contract works insurance cover depends on the insurer, policy wording, project value, contract conditions and the risks selected. However, most policies are built around a core idea: protecting the works in progress if they are damaged by an insured event before completion or handover.
This article explains common inclusions, common exclusions, limits and practical questions to ask before relying on a policy. It is general information only and does not take into account your objectives, financial situation, project obligations or insurance needs.
What is contract works insurance?
Contract works insurance is a type of construction insurance cover that may respond when insured building works are accidentally lost, damaged or destroyed during the construction period. It is sometimes described as building works insurance, construction works insurance or site insurance.
Depending on the policy, cover may be arranged for:
- a single construction project;
- multiple projects under an annual turnover-based policy;
- residential building works;
- commercial or industrial construction;
- civil works, infrastructure or fit-out projects; or
- renovations, alterations and extensions.
Some policies focus only on material damage to the works. Others may be packaged with public liability or other extensions. It is important not to assume that all construction-related risks are automatically covered under one policy.
If you are comparing options for a project, you can start from the Contract Works Insurance page to understand quote pathways and the types of project information insurers or brokers may request.
Common contract works insurance inclusions
Although every policy is different, contract works insurance commonly focuses on damage to insured property connected with the construction project. The following areas are often considered when assessing construction insurance cover.
The contract works themselves
The main item insured is usually the physical work being constructed. This may include the building, structure, alterations, additions, fit-out or civil works specified in the construction contract.
For example, if a partially completed building is damaged by an insured fire or storm event, the policy may cover the cost to repair or reinstate the insured works, subject to the policy terms, limits and excess.
Materials intended for the project
Policies may cover building materials, fixtures and fittings intended to form part of the works. This can include materials stored on site, and in some cases materials stored off site or in transit if the policy includes those extensions.
This detail matters because construction projects often involve staged deliveries, off-site fabrication or materials being held before installation. If off-site storage or transit cover is important, it should be specifically checked rather than assumed.
Temporary works and site structures
Some policies may include temporary works needed to complete the project, such as scaffolding, formwork, hoardings, temporary fencing or site sheds. Cover can vary significantly, particularly where items are hired, owned by subcontractors or insured under another policy.
Builders should check whether temporary works are included in the insured value and whether there are sublimits or conditions for temporary site structures.
Accidental damage
Contract works insurance commonly responds to sudden and accidental physical damage to insured works. This might include damage caused by an unexpected site incident, impact or mishap, provided the event is not excluded.
However, policies usually distinguish between accidental damage and the cost of correcting defective work, poor design, faulty materials or non-compliant construction. That distinction is one of the most important limitations to understand.
Fire, storm, theft and malicious damage
Many policies may include cover for events such as fire, storm, theft, vandalism or malicious damage. The scope of cover can depend on conditions such as site security, storage arrangements, weather protection, whether the site was unattended and whether the event falls within any exclusion.
For example, theft of unfixed materials may be treated differently from theft of installed items, and some policies may require reasonable precautions or specified security measures.
Removal of debris and professional fees
Some policies include additional costs that arise after an insured loss, such as removing debris, demolition costs, architects' or engineers' fees, or costs required to reinstate the works. These items may be included within the main sum insured or subject to separate sublimits.
These extensions can be valuable after a major loss, because the cost of rebuilding is not always limited to replacing materials and labour.
Maintenance or defects liability period cover
Some contract works policies include limited cover after practical completion during a maintenance or defects liability period. This does not mean every defect is covered. The cover may only apply to damage that occurs during maintenance work or damage arising from a cause that happened during the construction period.
The start and end dates of this period should be checked carefully against the construction contract.
What contract works insurance usually does not cover
Understanding contract works insurance exclusions is just as important as understanding inclusions. Exclusions vary between insurers, but the following are common areas that may be excluded, limited or require separate cover.
| Risk or cost | Why it may not be covered |
|---|
| Defective workmanship | The cost of fixing poor workmanship is commonly excluded, although resulting damage may be treated differently depending on the wording. |
| Faulty design or specification | Design errors, professional mistakes or unsuitable specifications may require professional indemnity cover rather than contract works cover. |
| Wear and tear or gradual deterioration | Insurance is generally intended for sudden insured events, not normal ageing, corrosion, rot or gradual damage. |
| Existing structures | Damage to pre-existing buildings may not be covered unless the policy specifically includes existing property or surrounding property. |
| Plant, tools and equipment | Contractors' tools, plant and machinery may need separate plant and equipment cover. |
| Delay costs and penalties | Liquidated damages, loss of profit, contract penalties and delay-related costs are commonly excluded unless a specific cover applies. |
| Employee injuries | Workplace injuries are generally dealt with under workers compensation arrangements, not contract works material damage cover. |
| Public liability claims | Injury or property damage claims made by third parties usually require public liability insurance, even if packaged with a contract works policy. |
Defective work versus resulting damage
A key issue is the difference between the defective part of the work and damage that results from it. A policy may exclude the cost of replacing faulty work itself, but may provide some cover for other insured property damaged as a consequence. This depends heavily on the wording and any defects exclusion.
For example, if incorrectly installed flashing causes water damage to other completed works, the policy response may depend on how the exclusion is drafted, whether the damage was sudden, and whether the affected property is insured under the policy.
Existing buildings and renovation work
Renovations, alterations and extensions can create a higher risk of misunderstanding. The new works may be insured, but the existing building may be excluded or only partly covered unless existing structures cover is specifically arranged.
This is especially important for residential renovation projects where damage to the existing home could be more expensive than the value of the new works.
Subcontractors and other insured parties
Contract works policies may name or note principals, head contractors, subcontractors or financiers as insured parties, depending on the contract and policy structure. However, being involved in the project does not automatically mean a subcontractor's own tools, liability, workmanship obligations or professional exposures are covered.
Builders should check who is insured, what each party is insured for, and whether the construction contract requires particular parties to be noted on the policy.
Limits, sublimits and excesses to check
Even when a risk is covered, the amount payable may be limited. Policy limits and sublimits are central to understanding the practical value of site insurance.
Sum insured or contract value
The main limit is usually based on the contract value or estimated completed value of the works. If this amount is too low, there may be a shortfall after a major claim. Some policies may also apply underinsurance or average clauses if the declared value is inadequate.
The insured value may need to account for materials, labour, escalation, professional fees, demolition, removal of debris, temporary works and any variations. The correct basis will depend on the policy wording.
Single project versus annual policy limits
A single project policy usually applies to one specified project. An annual policy may cover multiple projects during the policy period, subject to declared turnover, maximum project values, project types and any notification requirements.
An annual policy may still have limits for any one contract, any one location or any one event. Builders should confirm whether their largest project fits within the policy parameters.
Sublimits for specific extensions
Some items may have their own sublimits, even where the main sum insured is higher. Common examples can include:
- materials in transit;
- off-site storage;
- temporary works;
- expediting expenses;
- professional fees;
- debris removal;
- plans and documents;
- testing and commissioning; and
- existing property or surrounding property.
A sublimit can materially affect a claim outcome, so it should be reviewed against the way the project will actually be delivered.
Excesses
The excess is the amount the insured contributes towards a claim. Different excesses may apply to different types of events, such as storm, theft, water damage or high-risk works. A higher excess may reduce premium in some cases, but it also changes the amount retained by the business if a claim occurs.
Policy conditions that can affect a claim
Contract works insurance is not only about what is listed as covered or excluded. Conditions can also affect whether and how a claim is paid.
Common conditions may relate to:
- reasonable precautions to prevent loss or damage;
- site security and theft prevention;
- compliance with laws, codes, permits and contractual requirements;
- hot works procedures;
- weatherproofing and storm preparation;
- storage of materials;
- notification of project changes or increased values;
- time limits for project completion;
- cessation or abandonment of works; and
- prompt claims notification and cooperation with the insurer.
If a condition is not followed, the insurer may review whether that has affected the loss or the claim. The outcome will depend on the circumstances and the policy wording.
Contract works insurance and public liability are not the same
Contract works insurance and public liability insurance are often discussed together, but they address different risks.
Contract works cover is generally concerned with physical loss or damage to the insured works and related property. Public liability insurance is generally concerned with claims by third parties for personal injury or property damage connected with the business or project.
For example, storm damage to partially completed works may be a contract works issue. A visitor being injured by site activity may be a public liability issue. Some construction insurance packages include both, but the covers remain separate sections with separate limits, exclusions and conditions.
Examples of how cover may apply
The following examples are simplified and should not be treated as claims outcomes. Actual results depend on the policy and facts.
| Scenario | Possible insurance issue |
|---|
| A fire damages a partly completed townhouse project. | May fall within contract works cover if fire is insured and the damaged works are within the policy period and sum insured. |
| Unfixed appliances are stolen from an unsecured site. | May depend on theft cover, site security conditions, whether the items were insured materials and any sublimit. |
| A design error requires part of the structure to be rebuilt. | The cost of correcting the design issue may be excluded or require another type of cover. |
| A storm damages new works and the existing house during a renovation. | The new works may be treated differently from the existing structure unless existing property cover is included. |
| A subcontractor's tools are stolen from the site. | Tools may not be covered under the contract works section and may require separate equipment insurance. |
Questions to ask before choosing or relying on a policy
Before arranging building works insurance, builders and contractors may wish to ask:
- What exactly is included in the insured contract works?
- Are materials covered on site, off site and in transit?
- Are temporary works, scaffolding or hired items included?
- Is theft covered, and what security conditions apply?
- Are storm, flood, water damage or bushfire treated differently?
- Does the policy cover existing structures for renovation work?
- Who needs to be named or noted as an insured party?
- What is the maximum project value under the policy?
- Are there sublimits for debris removal, professional fees or expediting costs?
- What exclusions apply to defective workmanship, design and materials?
- Does the policy include a maintenance or defects liability period?
- What excesses apply to different types of claims?
- What changes must be notified during the project?
Because construction contracts and insurance wordings can be technical, many builders use a broker to help compare policy structure, limits and exclusions. You can review available support through the Brokers page if you need help interpreting options for a project.
How to read a contract works insurance schedule
The policy schedule is the summary of the cover arranged. It should be read together with the full policy wording, endorsements and any notices. Important items to check include:
- the insured name and any additional insured parties;
- the project address or policy territory;
- the policy period and any maintenance period;
- the contract value or maximum project value;
- the sections of cover selected;
- limits, sublimits and excesses;
- special conditions or endorsements;
- excluded activities or project types; and
- requirements for notifying changes or variations.
If the construction contract requires specific insurance arrangements, the policy schedule should be compared with those requirements before work starts.
Key takeaway
Contract works insurance commonly covers insured building works, project materials and certain temporary works against physical loss or damage from insured events such as fire, storm, theft, vandalism or accidental damage. However, cover is subject to exclusions, limits, sublimits, excesses and conditions.
The biggest traps are assuming that defective work, existing structures, tools, delay costs, professional mistakes or public liability claims are automatically included. They may not be. Builders and contractors should review the policy wording, project contract and declared values carefully, and seek professional assistance where needed.
Published: Thursday, 17th Sep 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.