The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Contract works insurance may cover more than the head builder, but who is protected depends on the policy wording, project contract and how each party is listed. This guide explains how subcontractors, owners, principals, financiers and other interested parties may fit into a construction insurance arrangement.
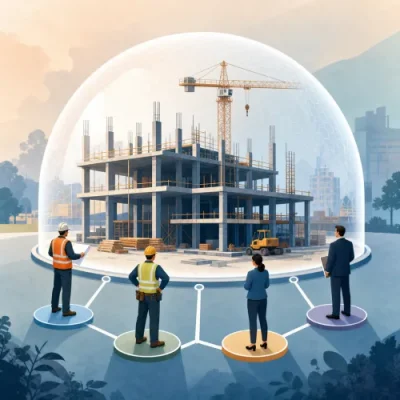
Contract works insurance is often arranged by a builder or head contractor, but construction projects usually involve more than one party. Subcontractors, owners, principals, financiers, project managers and joint venture partners may all have an interest in the works being completed and protected.
So, does contract works insurance cover subcontractors, owners and principals? It can, but not automatically in every situation. Cover depends on who is named or defined as an insured, who is listed as an interested party, what the project contract requires and what the policy wording actually says.
This article explains the common ways parties may be included under a contract works insurance policy in Australia, what that inclusion may and may not mean, and why subcontractors and principals should not assume they are fully protected without checking the details.
Who is usually insured under a contract works policy?
A contract works policy is designed to protect the construction works during the project period. It commonly responds to accidental physical loss or damage to the insured works, subject to the policy terms, exclusions, limits and excesses.
The primary insured is often the builder, head contractor or construction business arranging the policy. However, the policy may also extend to other parties involved in the project, depending on the wording and schedule.
Commonly relevant parties include:
- The builder or head contractor: usually the party responsible for arranging the cover and delivering the works.
- Subcontractors: trades or specialist contractors performing part of the works.
- The owner or principal: the party engaging the builder or receiving the completed project.
- Developers: where a development entity owns or controls the project.
- Financiers or mortgagees: lenders with a financial interest in the property or project.
- Joint venture partners: where the project is delivered by more than one contracting entity.
- Project managers or consultants: in some cases, if the contract or policy wording recognises their role.
The key point is that involvement in the project does not necessarily mean full insurance protection. The policy needs to identify who is insured, what they are insured for and whether any conditions apply.
Does contract works insurance cover subcontractors?
Contract works insurance may cover subcontractors for their interest in the insured works, but this depends on the policy wording. Some policies define the insured broadly enough to include subcontractors while they are performing work on the project. Others may only cover subcontractors if they are specifically included or if the contract requires them to be covered.
Even where subcontractors are included, that does not mean they are covered for every risk connected to their business. The policy may only protect the physical construction works, materials or temporary works that form part of the insured project.
What subcontractor inclusion may cover
Where a subcontractor is treated as an insured under the contract works section, cover may apply to accidental loss or damage to the insured works connected with the project. For example, if an insured event damages partially completed building works, the policy may respond for the repair or reinstatement of those works, subject to policy terms.
This can be important because subcontractors may have materials, labour and completed work tied up in the project before final payment is made.
What subcontractor inclusion may not cover
A subcontractor should not assume the head contractor's contract works policy replaces their own insurance arrangements. Depending on the business and work performed, subcontractors may still need to consider separate cover for:
- public liability for injury or property damage claims arising from their work;
- tools, plant and equipment;
- commercial motor vehicles;
- workers compensation obligations where applicable;
- professional indemnity if they provide design, engineering or other professional services;
- their own business interruption or income protection needs;
- defects, faulty workmanship or rectification costs that may be excluded or limited.
Contract works insurance and subcontractor insurance are related, but they are not the same thing. A subcontractor may be covered for some project works under the head policy while still needing their own policies for liabilities and business assets.
How do owners and principals fit into contract works insurance?
In construction contracts, the owner or principal is usually the party for whom the works are being carried out. This may be a homeowner, commercial property owner, developer, government-related entity or another project principal.
A principal may be included in a contract works policy in different ways. The two common concepts are being a named insured or being noted as an interested party.
Principal insured contract works arrangements
When a principal is included as an insured, they may have direct protection under the policy for their interest in the insured works. This can be important if the principal has a contractual or financial exposure to loss or damage during the construction period.
Some contracts require the policy to be arranged in the joint names of the contractor and principal. This may help ensure both parties have recognised interests under the contract works cover. However, the practical effect depends on the policy wording, the contract, any endorsements and how claims are handled.
Interested parties and noted interests
An owner, principal, financier or other stakeholder may instead be listed as an interested party. Being noted as an interested party generally recognises that the party has a financial or contractual interest in the project or property.
However, being noted is not always the same as being fully insured. It may not give the interested party the same rights as a named insured, and it may not provide cover for their own liabilities. The wording and schedule should be checked carefully.
| Party status | What it may mean | What to check |
|---|
| Named insured | The party is specifically identified as insured under the policy. | Which sections apply, policy limits, exclusions and claims rights. |
| Additional insured | The party is added to the policy, often for a particular project or role. | Whether cover is limited to certain works, activities or liability exposures. |
| Interested party | The party's financial or contractual interest is noted. | Whether this creates direct cover or only recognises an interest. |
| Not mentioned | The party may not have direct protection under the policy. | Whether the policy definition of insured is broad enough to include them. |
Why project contracts matter
The construction contract is often the starting point for deciding who should arrange insurance and who should be covered. Tender documents, head contracts and subcontracts may specify insurance requirements, including:
- who must arrange the contract works policy;
- the minimum insured value or project sum;
- whether the principal must be named or noted;
- whether subcontractors must be included;
- required public liability limits;
- cover for existing structures, temporary works or materials off-site;
- evidence of insurance, such as a certificate of currency;
- whether waivers of subrogation or cross-liability clauses are required.
Insurance arrangements should be consistent with the contract. If the policy does not match the contractual obligation, a party may believe cover exists when the insurer has not agreed to provide it.
Where there is any uncertainty, it may be appropriate to seek help from a suitably qualified insurance professional or legal adviser before signing the contract or starting work.
Contract works cover is not the same as public liability
One common source of confusion is the difference between contract works insurance and public liability insurance.
Contract works insurance generally focuses on accidental loss or damage to the insured construction works, materials and sometimes temporary works. Public liability insurance generally focuses on claims by third parties for injury or property damage arising from business activities, subject to the policy terms.
For example, damage to partially completed works caused by an insured event may be a contract works issue. Injury to a visitor or damage to a neighbouring property may be a public liability issue. Faulty workmanship, design errors, defective materials and gradual deterioration may involve further limitations or different types of cover.
Because construction losses can involve more than one policy section, it is important to understand what each party's insurance is intended to do.
Questions subcontractors should ask before relying on a head policy
If you are a subcontractor, it can be risky to assume the builder's or principal's insurance fully protects you. Before relying on another party's policy, consider asking:
- Am I included in the definition of insured for this project?
- Does the policy cover my work, supplied materials or temporary works?
- Am I covered only while on site, or also for materials stored off-site or in transit?
- Does the policy include public liability for subcontractors, or do I need my own liability policy?
- Are my tools, plant or equipment covered?
- Who pays the excess if a claim involves my work?
- Are there exclusions for defective workmanship, design or materials?
- Does the policy include a waiver of subrogation in favour of subcontractors?
- Can I receive a certificate of currency or written confirmation of my status?
Subcontractors should also check their subcontract. It may require them to hold their own insurance regardless of any cover arranged by the head contractor.
Questions owners and principals should ask
Owners and principals also need clarity before work begins. Important questions may include:
- Who is responsible for arranging contract works insurance?
- Is the policy in the joint names of the builder and principal?
- Is the principal a named insured or only an interested party?
- Does the policy cover the full project value, including variations?
- Are existing structures covered if the project involves renovation, extension or alteration work?
- Are materials stored off-site or in transit covered?
- Does the policy satisfy the insurance requirements in the building contract or tender?
- What happens if the builder, subcontractor or principal contributes to the loss?
- Who will manage a claim and receive claim payments?
These questions are especially important for renovations and additions, where existing buildings and new works may need different treatment under the policy.
What does it mean to add an interested party?
Adding an interested party is common where another person or organisation has a financial stake in the works. Examples may include a property owner, principal, financier, mortgagee, landlord or developer.
The effect of noting an interested party can vary. In some cases, it may simply mean the insurer records that party's interest and may acknowledge them on the certificate of currency. In other cases, endorsements or contract requirements may give the noted party specific rights or protections.
Because the phrase "interested party" can mean different things in practice, it should not be treated as a substitute for checking the policy schedule and wording.
Common issues that can affect who is protected
The question of who is covered is not just administrative. It can affect claims outcomes, contractual disputes and who carries financial risk after a loss.
Common issues include:
- Incorrect insured names: if the legal entity on the policy does not match the contracting entity, cover can become more complicated.
- Unlisted principals or financiers: a stakeholder may expect to be recognised but not appear on the policy schedule.
- Subcontractor assumptions: subcontractors may assume they are covered for liability, tools or defective work when they are not.
- Project value changes: variations may increase the insured value beyond the original estimate.
- Existing structures: renovation projects may involve damage to parts of the property that are not automatically part of the contract works.
- Policy period gaps: cover may need to align with the construction period, defects liability period or handover arrangements.
- Multiple policies: where several parties hold insurance, policy interaction and claim responsibility may need to be managed carefully.
How to check whether the right parties are covered
The safest approach is to confirm the insurance structure before work starts, not after a loss occurs. A practical review usually involves:
- Read the construction contract: identify who must arrange insurance and who must be included.
- Check the policy schedule: look at named insureds, additional insureds, interested parties, project description, insured value and period of insurance.
- Review the policy wording: confirm how "insured", "principal", "subcontractor" and "contract works" are defined.
- Match the policy to the project: consider existing structures, demolition, materials in transit, off-site storage, temporary works and plant.
- Obtain written confirmation: ask for a certificate of currency or endorsement where required.
- Check related policies: confirm public liability, professional indemnity, tools, plant and workers compensation where relevant.
If the policy wording or contract requirements are unclear, speaking with a qualified insurance broker can help identify gaps before they become expensive problems. You can use the site's broker information page to understand how broker support may assist with contract works insurance enquiries.
Key takeaway
Contract works insurance may cover subcontractors, owners and principals, but the answer depends on the policy wording and how each party is listed. A subcontractor might be covered for their interest in the insured works but still need their own liability, tools and business insurance. A principal or owner may be named as an insured or noted as an interested party, but those positions can have different consequences.
Before relying on a policy, each party should confirm their status, the scope of cover and any exclusions or conditions. Construction projects involve shared responsibilities, and the insurance should be arranged to reflect the actual contract, project structure and risks involved.
Published: Thursday, 17th Sep 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.